What Does “Comprehensive” Insurance Actually Mean?
Comprehensive.
It is one of the most familiar words in insurance, and understandably one of the most reassuring.
When a policy is described as comprehensive, many people naturally interpret that to mean everything is covered.
The reality is more nuanced.
Comprehensive insurance generally provides broad protection against a range of insured events. But every policy still operates within agreed limits, conditions, exclusions, excesses and responsibilities.
Understanding that distinction can make a significant difference when you need your insurance to respond in an event or at claim stage.
Comprehensive Refers to the Breadth of Cover
Comprehensive insurance is designed to provide wider cover and protection than limited forms of insurance.
In motor insurance, for example, comprehensive cover may protect against accidental damage, theft, hijacking, fire and certain third-party liabilities, subject to the specific policy wording.
But the word comprehensive does not override the rest of the contract.
The policy still determines:
- What events are insured
- What limits apply
- What excesses are payable
- What is excluded
- What security measures are required
- What information must be disclosed
- What responsibilities sit with the policyholder
This is why two policies both described as comprehensive can still provide different protection. This is why policy holders need to understand the term and the definition of the insurance language, and definition of comprehensive.
Being Covered and Meeting the Conditions of Cover Are Two Different Things
This distinction becomes particularly important at claim stage.
Consider a comprehensively insured vehicle.
The policy may provide theft and hijacking protection, while also requiring an approved tracking device to be installed and operational.
The theft protection exists.
So does the security condition.
Similarly, household contents insurance may provide broad protection for belongings within the home while high-value items, portable electronics, jewellery or belongings regularly taken away from the premises must be specified or protected differently as it is not covered under your household contents.
The existence of comprehensive cover does not remove the conditions attached to individual risks.
Your Excess Still Applies
Another common misconception or understanding is that comprehensive insurance removes the policyholder’s financial contribution when claiming.
It does not necessarily do so, this depends on a specification in the policy itself.
An excess is the portion of an insured loss that remains payable by the policyholder, subject to the terms of the policy.
Different claims can also attract different excess structures.
This means understanding your excess is just as important as understanding the events your policy covers.
The first time you discover what your excess is should ideally not be when you need to claim. As a policy holder being informed and educated to these factors is important as it avoids unannounced costs at claim stage.
Modifications and Extras Still Need to Be Declared
This becomes particularly relevant with vehicles and motorcycles, if not most.
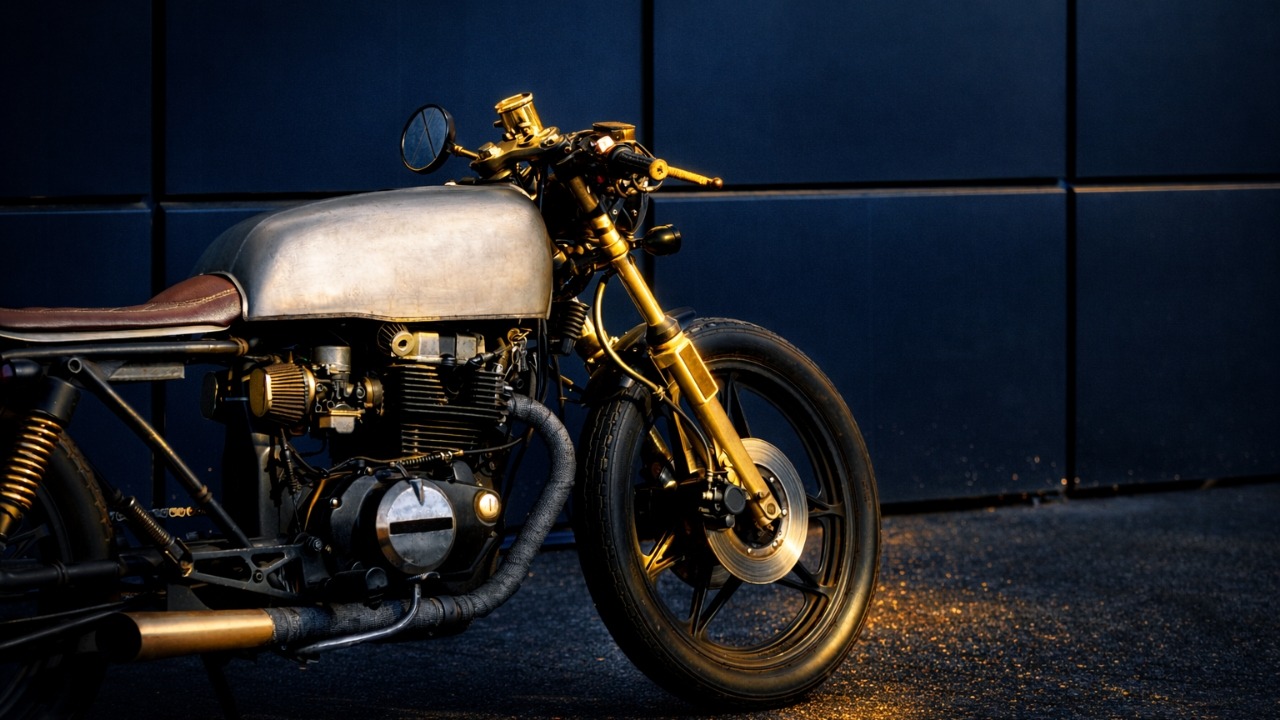
A motorcycle may leave the showroom in one configuration and look very different several years later.
Aftermarket exhaust systems, panniers, crash bars, navigation systems, auxiliary lighting, custom seats and performance modifications can add significant value.
Comprehensive insurance on the motorcycle itself does not necessarily mean every subsequently fitted accessory has automatically been incorporated at its full value.
Where disclosure or specification is required, those details matter.
A similar principle can apply to upgraded equipment in homes, businesses and watercraft.
Some Belongings Need Different Protection Outside the Home
Household contents insurance is another good example of why understanding the structure of cover matters.
A laptop, for example, will not be protected under your contents of your home, even though it remains in the house.
If you don’t leave your laptop at home all day, this condition changes as well.
The same applies to jewellery, watches, cameras and other portable valuables.
This is where solutions such as All Risks cover may become relevant, subject to the policy and item concerned.
Insurance should follow the reality of how an asset is used, in everyday life.
Commercial Cover Carries Its Own Conditions
The same principle applies to businesses.
Comprehensive commercial protection does not mean every operational consequence is automatically insured.
Read our full article: Protecting Your Business Against Business Interruption
A business may insure its premises, stock and equipment but still require separate or specifically structured protection for exposures such as business interruption, liability, specialist equipment or particular operational risks.
Security warranties, alarm requirements and other conditions may also form part of the basis on which the insurer accepted the risk.
The detail matters because businesses are rarely exposed to only one type of loss.
Watercraft and Specialist Assets Need Specialist Thinking
The distinction becomes even more important with specialist assets.
Watercraft insurance, for example, can involve the hull, motors, fitted equipment, sails, rigging, liability exposure, salvage costs and specified accessories.
Motorcycles may involve specialist parts, modifications, tyre protection, security requirements and different usage patterns.
The broader the lifestyle surrounding an asset becomes, the more important it is to understand exactly how the insurance surrounding it has been structured.
The Important Question Is Not Simply “Am I Comprehensively Insured?”
A better question is:
What does comprehensive mean under my specific policy?
Understanding your insurance means knowing:
- What is covered?
- What isn’t covered?
- What excess applies?
- What limits exist?
- What must be specified?
- What security requirements applies?
- What changes need to be disclosed?
None of this makes comprehensive insurance less valuable. It makes understanding it more valuable.
Clarity Before Claim Stage
Insurance terminology can make complex protection sound deceptively simple.
The purpose of good advice is to bridge that gap.
Golden Shield believes clients should understand the protection surrounding their lives, businesses and assets, rather than only discovering the detail when something goes wrong.
Because comprehensive protection works best when there is comprehensive understanding.
Unsure What Something on Your Policy Means?
You should never feel uncomfortable asking what a condition, exclusion, excess or benefit means. That drives the purpose of your advisor.
Speak to a Golden Shield advisor for clarity on how your insurance works and what the terms of your cover mean in practice.